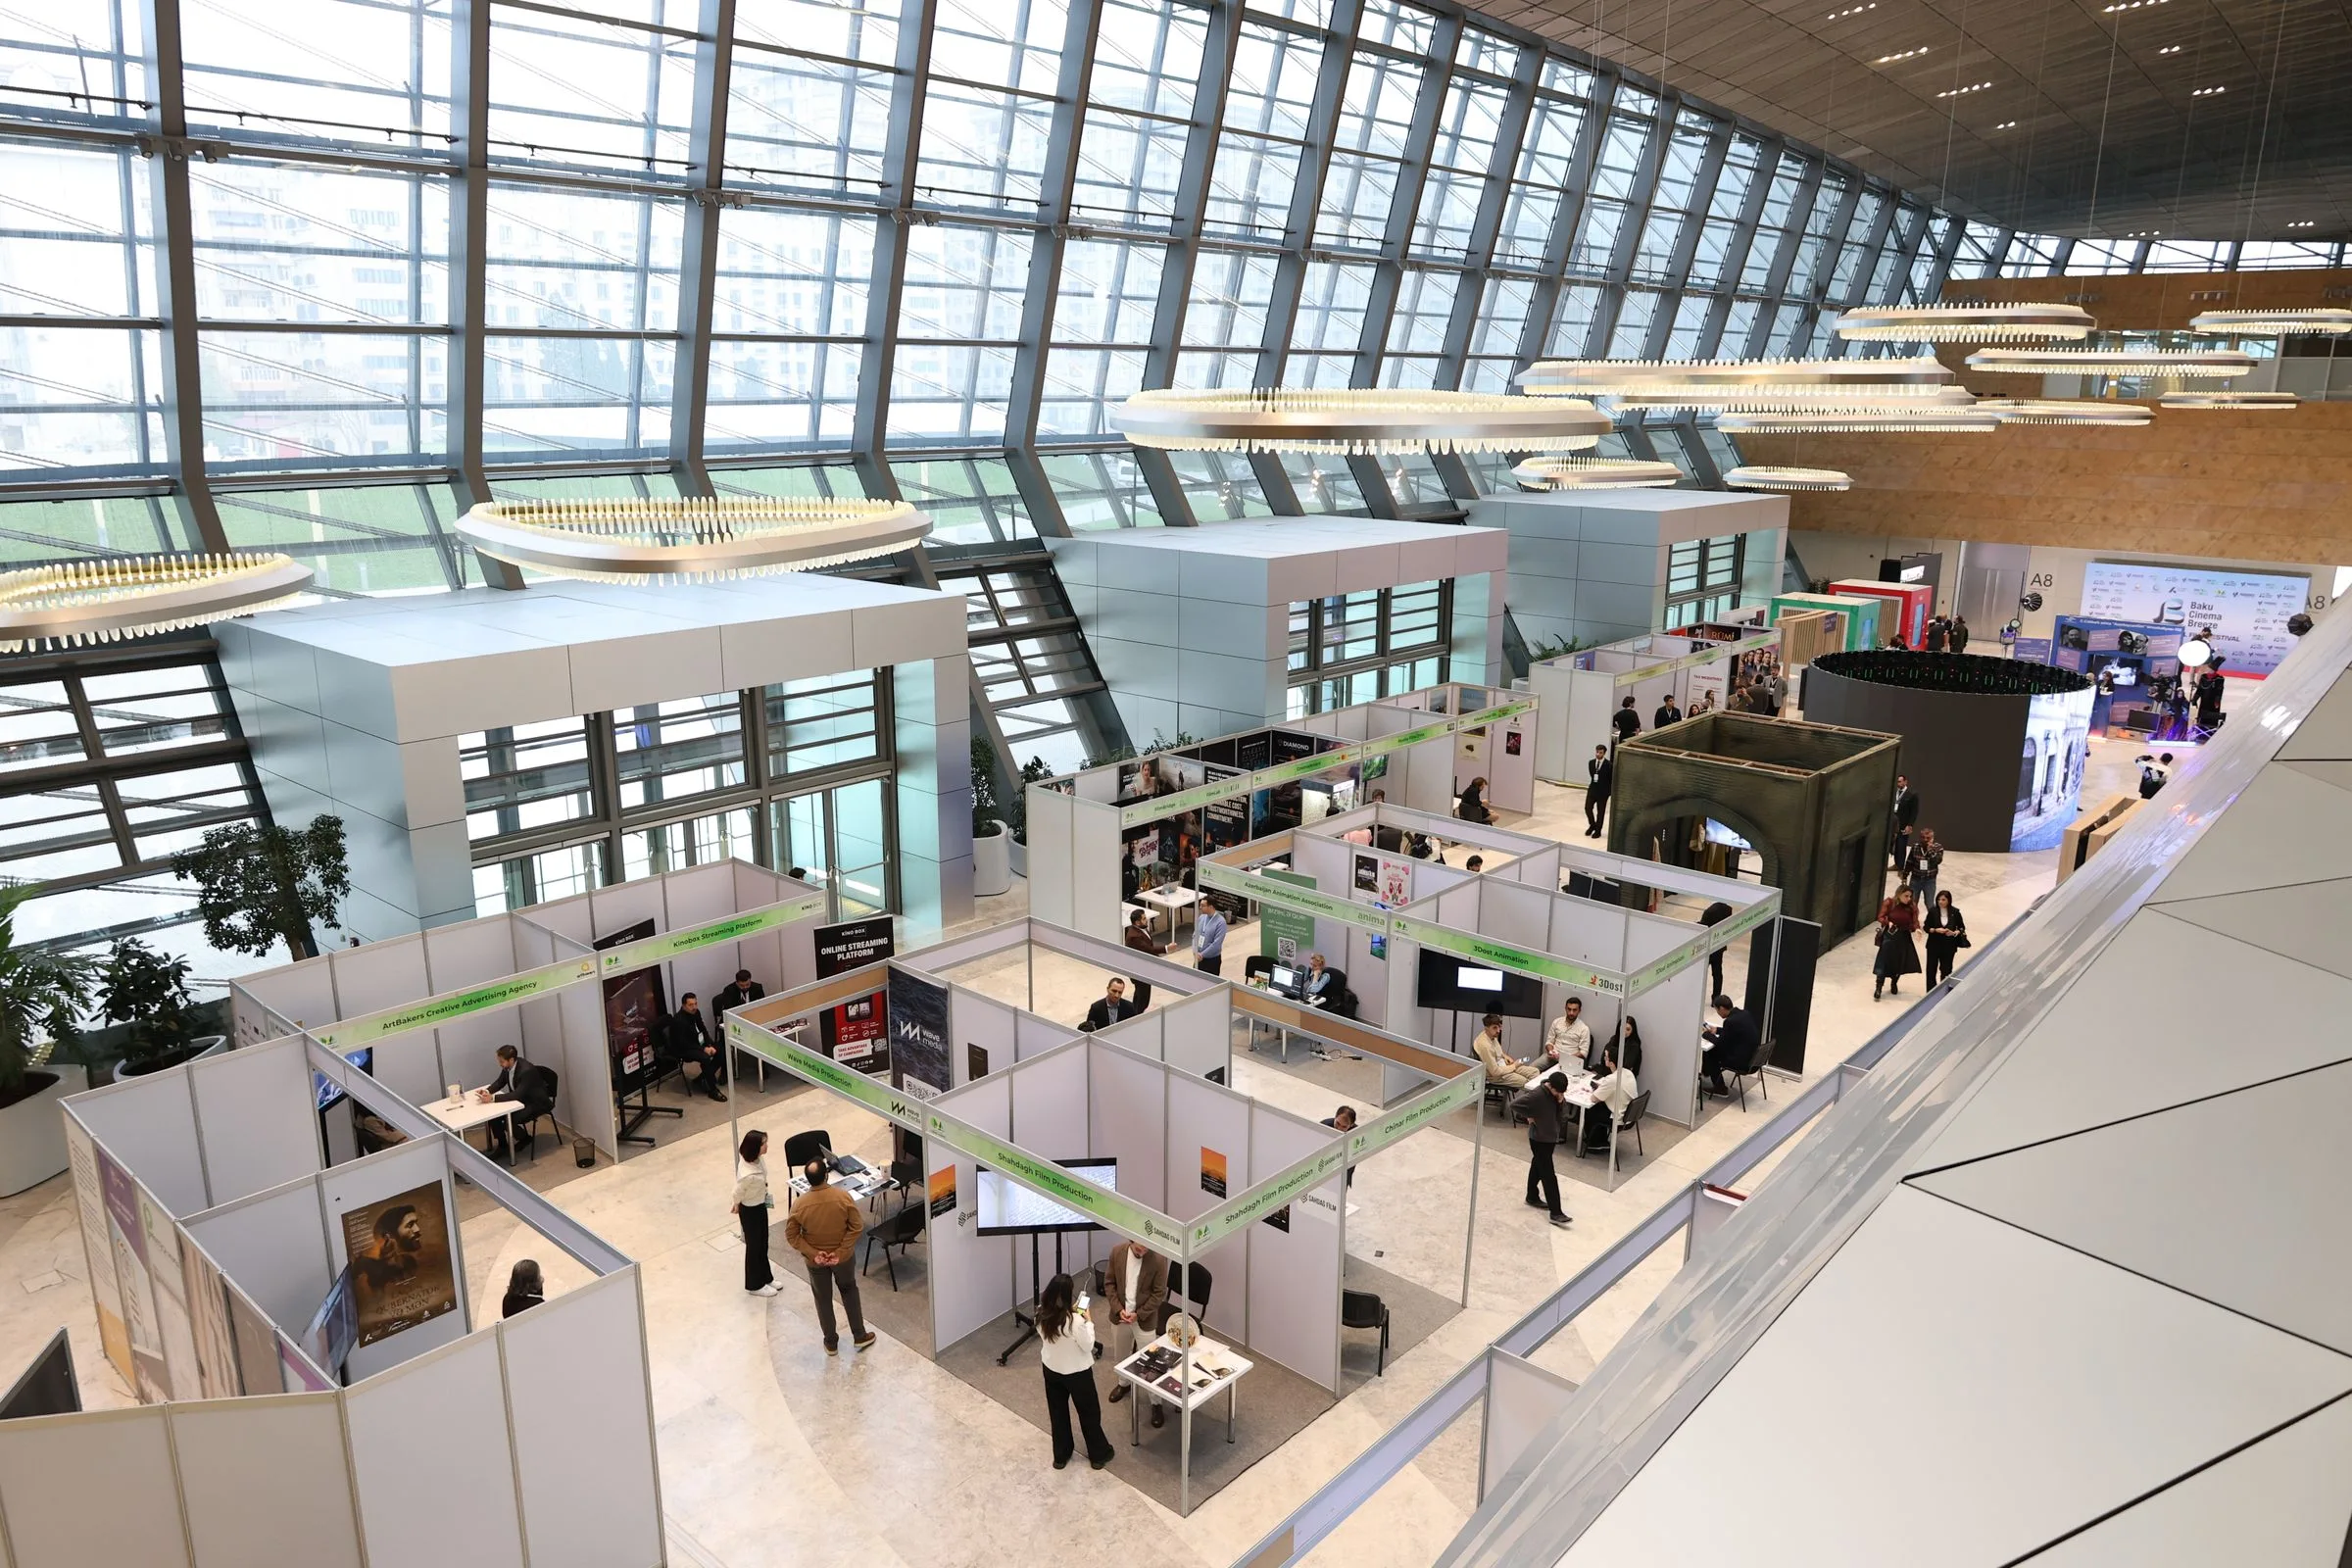
The NFDA International Convention & Expo lands in Charlotte October 25–28. Three hundred exhibitors, thousands of attendees, and a program built around the themes the association chose months ago.
Here is what the program will not tell you: the five structural forces reshaping funeral home M&A right now. They will be confirmed in Charlotte — not from the stage, but from the exhibit hall, the hotel bar, and the corridor conversations between sessions. If you are evaluating an acquisition in the next twelve months, these realities will shape your deal more than any keynote.
This is not a networking guide. We already published a convention networking playbook. This is predictive market analysis — what the convention’s timing, exhibitor mix, and industry backdrop will ratify about the landscape you are buying into.
Why the Convention Floor Tells You More Than the Sessions
The formal program is useful. It is also six to twelve months behind the market.
Conference sessions are proposed, reviewed, and scheduled on long timelines. By the time a panel reaches the ballroom, the reality it describes has already moved. The October SBA rule changes took effect September 30. No session was built around them because they were not finalized when programming closed.
The exhibit hall operates on a different clock. Exhibitors commit booth space based on where they think money is flowing right now. A CRM vendor buying a double booth is making a bet on their pipeline. A PE platform hosting a private dinner is signaling acquisition appetite. A lender conspicuously absent from the floor is telling you something about their risk appetite.
What to watch:
- Who is buying booth space. New exhibitors — especially technology vendors, lenders, and advisory firms — reveal where capital sees opportunity.
- Which PE platforms are hosting dinners or receptions. Private events signal active deal flow. If three platforms are hosting and two are new to the space, international or institutional capital is circling.
- Which vendors are pitching to multi-location operators vs. independents. This tells you who the technology market thinks will own these businesses in five years.
- Which lenders showed up and which stayed home. A lender who was on the floor last year and is absent this year has repriced their risk.
The hallway is the leading indicator. The stage is the lagging one.
Reality #1: The SBA October Rules Are Already Reshaping Who Can Buy
SOP 50 10 8.1 took effect October 1, 2026. The convention lands three and a half weeks later. That timing matters — Charlotte will be the first major industry gathering where the new rules have had time to stall real deals.
Three changes hit funeral home buyers directly:
- Citizenship narrowing. Permanent residents with certain visa categories now face additional documentation requirements. In a market where immigrant entrepreneurs have been active acquirers, this shrinks the buyer pool.
- Mandatory quality of earnings (QoE) reports. Previously optional for smaller deals, a QoE is now required on SBA 7(a) loans above $500,000. That adds $15,000–$40,000 to closing costs and two to four weeks to the timeline. For a $1.2M funeral home acquisition, this is not trivial.
- 1.25x debt service coverage ratio (DSCR) floor. Lenders always had internal DSCR requirements. Now the SBA has codified a minimum. Deals that would have squeezed through at 1.15x no longer qualify. The marginal acquisition — the one where the buyer’s projections had to be optimistic — is off the table.
What you will hear in Charlotte: Stories. The rule changes are three weeks old. There is no published data yet on how many deals stalled, how many buyers were disqualified, or how many lenders adjusted their criteria. The data is entirely anecdotal — and Charlotte is where anecdotes become consensus.
Listen for:
- Lenders describing specific deals that fell apart under the new requirements.
- Brokers reporting buyer pools that shrank by a third or more.
- Sellers who pulled listings because the financing environment shifted.
This is intelligence you cannot get from a press release or an industry report. It exists only in conversation, and the convention concentrates those conversations into four days.
Reality #2: The Workforce Crisis Is No Longer About Recruiting — It’s About Whether Operations Are Viable
NFDA flagged “workforce challenges” as a convention theme. That framing undersells the problem.
The numbers are stark. According to Bureau of Labor Statistics data, the funeral service workforce is aging out. In the worst-affected states, there are roughly 51 licensed funeral directors per 100 open positions. A third of currently licensed directors are over 65. Mortuary science program enrollment has been flat for a decade.
This is not a recruiting problem. Recruiting implies there is a pool of candidates and you need to attract them. In several markets, the pool does not exist.
For a buyer, this reframes the acquisition question entirely. The staffing crisis is not an HR challenge you solve after closing. It is an operational viability question you must answer before you sign.
The questions Charlotte will surface:
- Which states are functionally short? Not every market is equally affected. Some states have maintained mortuary school pipelines. Others have not. The convention will surface the worst markets through conversations with operators who are living it.
- What are operators paying? Compensation data in funeral service is notoriously opaque. Charlotte will give you real numbers — what an embalmer commands in the Southeast vs. the Midwest, what signing bonuses look like, what retention packages are costing.
- Are any operators solving it? Some multi-location groups have built apprenticeship pipelines or partnered with mortuary schools. If a solution exists, it will be visible in Charlotte. If no one has cracked it, that tells you something too.
What This Means for Your Underwriting
If you are modeling an acquisition in a workforce-constrained state, your staffing assumptions need stress testing. Model the cost of:
- A six-month vacancy in your lead director role.
- Compensation increases of 15–25% over three years to retain licensed staff.
- Travel coverage — flying in a licensed director from another market to cover cases.
If the deal does not work with those numbers, the deal does not work. Charlotte will tell you whether those numbers are conservative or optimistic.
Reality #3: Technology Exhibitors Are Betting on Multi-Location Operators, Not Independents
Walk the technology section of the exhibit hall with one question: who is this product built for?
The major case-management and CRM platforms — Passare, CRaKN, Parting Pro — have been shifting their feature roadmaps for two years. Cloud-based architecture. Multi-location administrative dashboards. Centralized reporting across facilities. Role-based access for regional managers. These are not features built for a single independent funeral home. They are features built for platforms operating ten, twenty, fifty locations.
Why this matters to a buyer:
- Pricing follows design. If technology vendors are designing for multi-location operators, they will price for multi-location operators. Per-location licensing at scale is cheaper than single-location licensing. The independent buyer’s technology stack will cost more per location than the consolidator’s.
- Feature gaps will widen. An independent buyer using the same CRM as a fifty-location group is paying for features they do not use. The alternative — a cheaper, simpler tool — means accepting a capability gap that grows every year.
- Integration is the real cost. A multi-location platform integrates accounting, case management, crematory scheduling, and preneed tracking in one system. An independent buyer cobbles together four or five tools and pays for the integration in staff time and data errors.
Conduct your own technology due diligence at the convention. Ask vendors directly:
- What percentage of your new customers are multi-location vs. single-location?
- Is your per-location price lower at ten locations than at one?
- Which features on your roadmap are multi-location only?
The answers will tell you whether the technology market has already decided the future of independent ownership.
Reality #4: International Capital Is Circling
NFDA 2026 is hosting FIAT-IFTA, the International Federation of Thanatology Associations. This brings international funeral operators and investors into the same room as US acquisition targets for the first time at this scale.
The most visible international player is Propel Funeral Partners, listed on the ASX (Australian Securities Exchange), which has disclosed approximately $182 million in acquisition capacity. Propel operates over 180 locations across Australia, New Zealand, and Singapore. The US market — fragmented, aging-owner-heavy, and culturally similar — is a logical expansion target.
But Propel is the one you can see. Private equity interest in death care has been well documented. What has been less visible is cross-border interest from operators and family offices in the UK, Canada, and continental Europe. FIAT-IFTA’s presence at NFDA puts those parties in a room where they can move from theoretical interest to specific conversations.
What this means for a buyer:
- Competition for targets increases. If international capital enters the US market seriously, it adds well-capitalized competitors to an already competitive acquisition landscape. These are not buyers who need SBA financing — they are buying with balance-sheet cash or foreign credit facilities unaffected by SOP 50 10 8.1.
- Valuations may inflate in target-rich markets. International acquirers often start in metros with international connectivity — Charlotte, Atlanta, Houston, Miami. If you are targeting those markets, pricing may shift.
- Due diligence timelines compress. A seller fielding interest from an international platform and a domestic independent buyer will lean toward the faster, more certain close. International operators with dedicated M&A teams close faster than a first-time buyer assembling advisors.
What to Watch in Charlotte
- International attendees at M&A-focused sessions and panels.
- Private receptions or dinners hosted by non-US entities.
- Advisory firms marketing cross-border transaction services.
If you see all three, international capital is no longer circling. It is landing.
Reality #5: The Cremation Technology Arms Race Has a Winner — and It’s Not the Independent
The NFDA statistics page projects the national cremation rate will exceed 64% by 2027. That trajectory is not news. What is news is what the equipment manufacturers on the exhibit floor are building to meet it.
Walk the cremation equipment section and you will see high-throughput, AI-monitored retort systems designed for volume. Automated loading, emissions monitoring, cycle optimization, remote diagnostics. These are not incremental upgrades to existing cremation equipment. They are capital-intensive systems that fundamentally change the economics of cremation.
The scale problem is straightforward:
- A next-generation retort system costs $350,000–$500,000 installed.
- A consolidator operating 50 locations with 5 crematories can amortize that investment across volume from dozens of homes.
- An independent buyer with one crematory serving one location cannot justify the capital expenditure at the same per-unit economics.
The result: cremation economics tilt further toward scale with every equipment generation. The independent operator is not priced out of cremation — they are priced out of efficient cremation.
What this means for your acquisition thesis:
- If the target owns a crematory, assess the equipment age and the capital required to stay competitive. A crematory built in 2010 is functional. It is also increasingly inefficient relative to what a consolidator is installing down the road.
- If the target does not own a crematory, model the outsourcing cost trend. As consolidators invest in high-throughput equipment, they may offer competitive outsourced cremation pricing — or they may raise prices to independents as a competitive lever.
- If your thesis depends on cremation margin, stress-test it against a competitor with next-generation equipment and ten times your volume. If the margin disappears, your thesis needs revision.
What a Buyer Should Do With This
Do not go to Charlotte with general interest. Go with a specific acquisition thesis and use the convention to stress-test it against these five realities.
Before You Go
- Map your target market against the five realities. Which ones apply? If you are targeting a workforce-constrained state with a cremation-dependent business and SBA financing, all five hit you. Prioritize accordingly.
- Prepare specific questions for specific people. Do not ask a lender “how’s business.” Ask them how many SBA 7(a) funeral home deals they have closed since October 1 and how many stalled on the new DSCR floor.
- Identify the exhibitors, lenders, and advisors you need to see. Review the exhibitor list before you arrive. Mark the technology vendors, the lenders, and the advisory firms. Plan your floor route.
While You Are There
- Spend more time on the exhibit floor than in sessions. The sessions are recorded. The corridor conversations are not.
- Ask technology vendors the multi-location question directly. Their answer is a market signal you cannot get from their website.
- Listen for SBA deal stories. Every lender, broker, and advisor will have one. Collect them. The pattern across twenty stories is the data.
- Watch for international attendees. Their presence is a signal. Their absence is also a signal.
After You Leave
Revisit your acquisition model. Apply what you learned. If two of the five realities undercut your assumptions, rework the deal before you proceed. Charlotte is where assumptions go to be tested. The best outcome is learning your thesis is wrong before you close, not after.
Key Takeaways
- The convention floor is a leading indicator. Exhibitor bets, lender presence, and corridor intelligence reveal market direction six to twelve months ahead of formal reports.
- SBA rule changes are already reshaping deal flow. The mandatory QoE and 1.25x DSCR floor have tightened the buyer pool. Charlotte is where the early impact data surfaces as anecdotes that will soon become consensus.
- Workforce viability varies by state. The national staffing crisis is a local operational question. Charlotte will surface which markets are functional and which are not.
- Technology is being built for consolidators. If vendors are designing and pricing for multi-location operators, the independent buyer’s cost disadvantage widens with every product cycle.
- International capital adds competition. FIAT-IFTA’s presence at NFDA 2026 moves cross-border interest from theoretical to actionable. Well-capitalized international buyers do not need SBA financing and are not affected by the October rule changes.
- Cremation equipment economics favor scale. Next-generation retort systems are capital-intensive investments that consolidators amortize across volume. The independent operator’s cremation margin is under structural pressure.
Go to Charlotte with a thesis. Come back with either confirmation or the knowledge that you need to revise it. Both outcomes are valuable. Only one of them is comfortable.
This article is for informational purposes only and does not constitute tax, legal, or financial advice. Consult qualified professionals for guidance specific to your situation. All trademarks belong to their respective owners. This publication is editorially independent and is not affiliated with, endorsed by, or sponsored by any franchisor or trade association mentioned herein.
For a comprehensive walkthrough of every step in the acquisition process, start with our complete guide to buying a funeral home. For convention-specific networking tactics, see the NFDA networking playbook.